
Omantel Share 2026: Growth, Dividends and Risks
Omantel entered 2026 after reporting one of its strongest financial years in recent history.Revenue increased. Profit jumped. Cash generation improved. Earnings per share rose sharply. The company also maintained its long-standing dividend policy.However, investors should look deeper than the headline numbers.A large part of Omantel Group’s business comes through Zain Group. Some 2025 profit growth also came from investment and business-combination gains.At the same time, Omantel carries significant debt.This creates an interesting investment case for Omantel stock in 2026.The company combines telecom stability, dividends, Zain exposure and growing technology businesses. However, investors should not expect the exceptional 2025 profit growth rate every year.Omantel’s Annual Report covers the Group and its subsidiaries for the year ended December 31, 2025.
Investing.com – Stock Market Quotes & Financial News
Investment Summary
Omantel enters 2026 with several positive factors.
- Group revenue increased 11.4% in 2025.
- EBITDA increased 10.6%.
- Profit attributable to Omantel shareholders increased 63.1%.
- Audited EPS reached 118 baisa.
- The company recommended a 55-baisa dividend.
- Operating cash flow increased by around 20%.
- Zain continues to provide regional growth.
- ICT, cloud, cybersecurity and IoT offer new opportunities.
- However, official net debt reached about OMR 2.90 billion.
- Omantel’s gearing ratio increased to 49.54%.
- 2026 revenue growth has continued, but investment gains helped reported profit.
Omantel 2025 Financial Results
The easiest way to understand Omantel is to compare 2025 with 2024.
| Financial Measure | 2025 | 2024 | Change |
|---|---|---|---|
| Group Revenue | OMR 3,413.1m | OMR 3,062.7m | +11.4% |
| EBITDA | OMR 1,155.4m | OMR 1,044.7m | +10.6% |
| Group Profit | OMR 371.0m | OMR 197.7m | +87.7% |
| Profit attributable to Omantel shareholders | OMR 88.4m | OMR 54.2m | +63.1% |
| Audited EPS | 118 baisa | 72 baisa | Strong increase |
| Recommended Dividend | 55 baisa | — | 47% payout |
Omantel’s audited revenue was OMR 3.413 billion in 2025. Profit for the year reached OMR 371.015 million.Profit attributable to Omantel shareholders reached OMR 88.423 million, compared with OMR 54.153 million in 2024.EBITDA increased to OMR 1.155 billion from OMR 1.045 billion.EBITDA means profit from operations before interest, tax, depreciation and amortisation.It helps investors understand the strength of the operating business.
EPS Jumped Strongly
Audited basic and diluted EPS reached OMR 0.118, or 118 baisa per share, in 2025.The audited comparative figure was OMR 0.072, or approximately 72 baisa, for 2024.Omantel’s Financial Review separately shows the restated 2024 EPS as 71 baisa because of presentation and rounding differences. For investment analysis, this article uses the audited consolidated statement figure.Omantel recommended a final dividend of 55 baisa per share for FY2025.The company states that this represents a 47% payout ratio.
The Important Story Behind Profit Growth
Omantel’s Group profit increased 87.7%.That looks extremely strong.However, investors should not simply assume another 88% increase in 2026.
The audited income statement shows that 2025 benefited from several items outside basic telecom operations.Investment income increased to OMR 39.7 million from OMR 11.4 million.Share of results from associates and joint ventures increased to OMR 42.0 million from OMR 7.5 million.Omantel also recorded an approximately OMR 53.1 million gain on a business combination.Therefore, part of the strong profit increase was not purely generated by normal telecom operations.This is very important for investors analysing Omantel stock in 2026.
Domestic Omantel Is Growing Steadily
Omantel’s domestic business produced a more normal growth picture.Domestic revenue increased from OMR 622.6 million in 2024 to OMR 676.1 million in 2025.That represents growth of 8.6%.
Domestic Revenue Comparison
| Business | 2025 | 2024 |
| Fixed Line | OMR 170.3m | OMR 163.4m |
| ICT & Emerging Technology | OMR 46.6m | OMR 29.8m |
| Mobile | OMR 186.7m | OMR 187.2m |
| Wholesale | OMR 213.1m | OMR 192.9m |
| Devices | OMR 59.4m | OMR 49.3m |
| Total | OMR 676.1m | OMR 622.6m |
ICT and Emerging Technology revenue increased around 56%, from OMR 29.8 million to OMR 46.6 million.Wholesale revenue also increased 10.5%.This supports Omantel’s strategy of becoming more than a traditional telecom company.
Future growth may increasingly come from:
Cloud computing, cybersecurity, AI, IoT, data centers, enterprise technology and international connectivity.
Domestic Profit Shows Some Pressure
Domestic EBITDA remained almost unchanged.It was OMR 180.4 million in 2025, compared with OMR 180.3 million in 2024.Domestic profit attributable to shareholders declined from OMR 69.7 million to OMR 65.2 million.Omantel explains that depreciation and amortisation increased 12% because of continued investment in networks, digital infrastructure and AI.In simple words, Omantel is spending heavily today to build infrastructure for tomorrow.
This can reduce accounting profit in the short term.
The important question for 2026 investors is whether these investments eventually produce higher profits and cash flows.
Operating Costs Are Rising

Domestic operating expenses reached OMR 617.3 million in 2025.That was a 9.3% increase from OMR 564.4 million in 2024.Cost of sales increased 12%. Operating and administrative expenses increased 6%. Depreciation and amortisation increased 12%.The domestic operating-expense-to-revenue ratio increased slightly from 90.7% to 91.3%. This is an important number to watch in 2026.Revenue growth is good, but investors should also see whether Omantel can control costs.
Omantel Still Leads Oman’s Telecom Market
Omantel continues to hold a powerful position in Oman.Fixed broadband subscriber market share increased from 54.4% to 54.9% during 2025.Mobile subscriber market share remained approximately 40.1%.This large customer base provides Omantel with an important competitive advantage.Telecom infrastructure is also expensive to build.This creates a natural barrier for new competitors.
5G Investment Supports Future Demand
Omantel continues investing heavily in its network.Its 5G network covered approximately 93.3% of Oman’s population by 2025.
Its 4G/LTE coverage reached approximately 98.4%.Fixed broadband services were accessible to more than 92% of households.The company spent OMR 129.3 million of capital expenditure during 2025.Much of this spending went toward 5G, digital infrastructure and AI.These investments may support long-term growth.However, they also increase depreciation and require cash.
Zain Is Omantel’s Biggest Growth Engine
Investors must understand that Omantel is no longer only an Oman telecom company.Its Zain exposure gives the Group access to several Middle Eastern and African markets.Zain Group revenue increased from OMR 2.499 billion to OMR 2.856 billion.That represents approximately 14.3% growth.Zain EBITDA increased from OMR 878.2 million to OMR 974.9 million.Zain net profit increased from OMR 200.8 million to OMR 354.7 million.
This diversification is valuable.
“Growth in Saudi Arabia, Iraq, Sudan and other markets can support Omantel’s overall results.However, international exposure also creates additional risks.”
Sudan Remains A Major Risk
Sudan is an important example.Its telecom operations produced strong financial growth during 2025.However, political instability and armed conflict remain serious risks.Omantel states that worsening hostilities could create further operational disruptions in Sudan.There is also an accounting issue.Omantel applies IAS 29 hyperinflation accounting to Sudan and South Sudan.
This makes financial comparisons more complicated.Investors should therefore avoid viewing Omantel simply as a low-risk domestic telecom company.
Otech Could Become A New Growth Engine
One of the most interesting parts of the Omantel investment story is its transformation into a technology company.
Omantel is expanding into:
Cloud computing, cybersecurity, data centres, AI, fintech, IoT and smart technology.
Otech is central to this strategy.Its IoT-related business has already shown strong growth.If Omantel can turn these new businesses into meaningful profits, the company could become less dependent on traditional voice and mobile services.That could improve its long-term growth potential.
Cash Flow Improved Strongly
Investors should not only examine accounting profit.Cash generation is equally important.Omantel generated OMR 935.1 million of net cash from operating activities in 2025.That compares with OMR 777.1 million in 2024.Operating cash flow therefore increased by approximately 20.3%.
This is a positive signal.
Strong operating cash flow helps Omantel:pay dividends, fund investments, service debt and maintain financial flexibility.
Understanding Omantel’s Cash Figures
Investors may see two different cash figures in Omantel’s financial statements.
The balance sheet reports OMR 409.5 million of cash and cash equivalents at December 31, 2025.
The cash-flow statement reports OMR 392.6 million.
The difference mainly comes from a OMR 16.89 million bank overdraft and a very small adjustment for deposits with maturities above three months.
For debt analysis, Omantel itself uses the OMR 409.5 million balance-sheet cash figure.
Debt Is The Main Financial Risk
This is the area investors should monitor most closely.
Traditional borrowings increased from OMR 2.574 billion in 2024 to OMR 2.853 billion in 2025.
However, the best measure is Omantel’s own official net-debt calculation.
Official Debt Position
| Measure | 2025 | 2024 |
| Borrowings including lease liabilities | OMR 3.310bn | OMR 2.972bn |
| Cash and cash equivalents | OMR 409.5m | OMR 296.5m |
| Net Debt | OMR 2.901bn | OMR 2.676bn |
| Gearing Ratio | 49.54% | 47.70% |
The Dividend Remains Attractive
Telecom companies often attract investors seeking regular income.
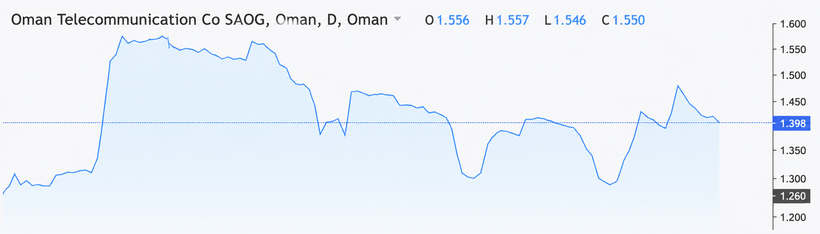
For FY2025, Omantel recommended a dividend of 55 baisa per share.The latest MSX snapshot checked for this analysis shows Omantel, ticker OTEL, at approximately OMR 1.398 per share.
At this price:
Dividend Yield = 0.055 ÷ 1.398 = approximately 3.93%.
This is not guaranteed future income.Future dividends depend on profit, cash flow, debt and capital-investment requirements.
Still, the dividend gives investors a return even if the share price moves slowly.
Is Omantel Stock Expensive?
Using the MSX price of approximately OMR 1.398, we can calculate several simple valuation measures.
| Valuation Measure | Approximate Value |
| Share Price | OMR 1.398 |
| 2025 EPS | OMR 0.118 |
| P/E Ratio | 11.8x |
| FY2025 Dividend | OMR 0.055 |
| Dividend Yield | 3.93% |
| Book Value Per Share | OMR 0.957 |
| Price-to-Book | 1.46x |
Omantel had OMR 717.407 million of equity attributable to company shareholders at year-end.
MSX reports 750 million issued shares.
Therefore:
Book value per share ≈ OMR 0.957.
At OMR 1.398, Omantel trades around 1.46 times book value.
A P/E ratio around 11.8 times does not look extremely expensive for a market-leading telecom company.
However, valuation should also reflect debt and the sustainability of earnings.
What Has Happened In 2026?
Omantel’s business growth continued into 2026.U Capital reported that second-quarter 2026 revenue increased 5% year-on-year.Revenue for the first half of 2026 increased approximately 6% year-on-year.Second-quarter net profit reached OMR 37.7 million, increasing 96% year-on-year.However, investors should again examine profit quality.
U Capital reported that much of the strong profit increase came from gains on strategic investments through Zain Ventures.This means investors should not assume that 96% quarterly profit growth represents Omantel’s normal operating growth rate.
Analyst Target Suggests Potential Upside
U Capital maintained a target price of OMR 1.682 per share following Omantel’s second-quarter 2026 results.Compared with an MSX price of OMR 1.398:
Potential price upside = approximately 20.3%.
If investors hypothetically added the previous 55-baisa annual dividend:
Potential total return would be approximately 24.2%.
This is only a mathematical illustration.It is not a guarantee or my prediction.The share price can move in either direction.
What Could Push Omantel Shares Higher?
Several developments could strengthen the investment case.
Domestic revenue could continue growing.ICT and emerging technology could maintain strong momentum.Otech could begin contributing meaningful profit.Zain could continue providing larger dividends.Operating cash flow could remain strong.Most importantly, Omantel could start reducing its OMR 2.9 billion net debt.
If these factors occur together, investors may become willing to pay a higher valuation for Omantel.
What Could Hurt Omantel Stock?
There are also important risks.
High Debt
Official net debt reached OMR 2.90 billion.Higher interest rates or weaker cash flows could make this debt more difficult to manage.
Rising Costs
Domestic operating expenses increased 9.3%.If costs continue rising faster than revenue, margins could come under pressure.
Heavy Capital Spending
5G, AI, cloud and digital infrastructure require large investment.These investments can increase depreciation before producing meaningful profit.
Competition
Price competition in mobile, broadband and digital services could reduce margins.
Technology Execution
Omantel is spending heavily to transform from a telecom company into a technology company.If Otech and other digital businesses fail to generate sufficient returns, investors may question that strategy.
What Investors Should Watch In 2026
Instead of looking only at share price, investors should follow six important numbers:
1. Domestic revenue growth
Revenue should continue growing above inflation.
2. Domestic EBITDA
This should eventually grow faster than it did in 2025.
3. ICT and Emerging Technology revenue
This is one of Omantel’s most important future growth areas.
4. Free cash flow
Technology investment must ultimately create cash.
5. Net debt
The current OMR 2.90 billion level should ideally begin declining.
6. Zain dividends
Higher Zain dividends can significantly support Omantel’s cash generation.
Final Investment View
Omantel enters 2026 from a relatively strong position.
Revenue is growing.Operating cash flow is improving.The company remains a market leader in Oman.Zain provides exposure to faster-growing regional telecom markets.The 55-baisa dividend provides an income element.At the same time, Omantel is trying to become much more than a traditional telecom operator.Cloud, cybersecurity, AI, IoT, fintech, data centres and enterprise technology could become increasingly important.This gives Omantel a growth story that many traditional telecom companies lack.
However, investors should remain careful.
The 87.7% increase in total Group profit during 2025 should not be treated as normal annual earnings growth.
Several investment and business-combination gains helped the result.
Domestic EBITDA was almost flat.
Domestic profit declined.
Net debt also increased to approximately OMR 2.90 billion.
Therefore, Omantel appears better described as a telecom income-and-growth company undergoing technology transformation, rather than a high-growth technology stock.At around 11.8 times 2025 earnings, the valuation does not appear excessive.A historical dividend yield near 3.9% also provides some income support.
But the strongest future investment case will depend on Omantel proving three things:
technology investments can generate profit, cash flow can remain strong, and debt can gradually decline.
If Omantel delivers these three outcomes, 2026 could become an important year in its transformation from Telco to TechCo.
Disclaimer: This article is for financial research and educational purposes only. It is not personal investment advice. Investors should conduct their own research before making investment decisions.